

Trading
Jelajahi berbagai pasar dengan harga kompetitif, likuiditas mendalam, dan alat trading canggih.
Pelajari Lebih Lanjut 
Platform
Trading dengan lancar menggunakan platform canggih TMGM, dibangun untuk kecepatan, presisi, dan pengalaman trading yang superior.
Pelajari Lebih Lanjut Platform Trading
Akademi
Pelajari dasar-dasar trading dengan sumber daya yang ramah pemula, termasuk panduan, webinar, dan wawasan pasar.
Pelajari Lebih Lanjut Berita & Analisis
Dapatkan update pasar real-time dan analisis ahli untuk tetap unggul dalam peluang trading
Pelajari Lebih Lanjut Berita & Analisis
Tentang
Pelajari apa yang membedakan TMGM — kehadiran global kami, kekuatan regulasi, dan komitmen terhadap inovasi dalam trading.
Pelajari Lebih Lanjut Mengapa Memilih TMGM
Sponsorship
Japanese Yen gives back most of its rally as Fed hike talk grows
- USD/JPY climbs above 158.00 and its 200-day average as Fed hike talk grows.
- Japan spent a record ¥15.4 trillion buying Yen from July 30 to August 26.
- BoJ's 1.25% rate takes effect Thursday, when Tokyo reopens after holidays.
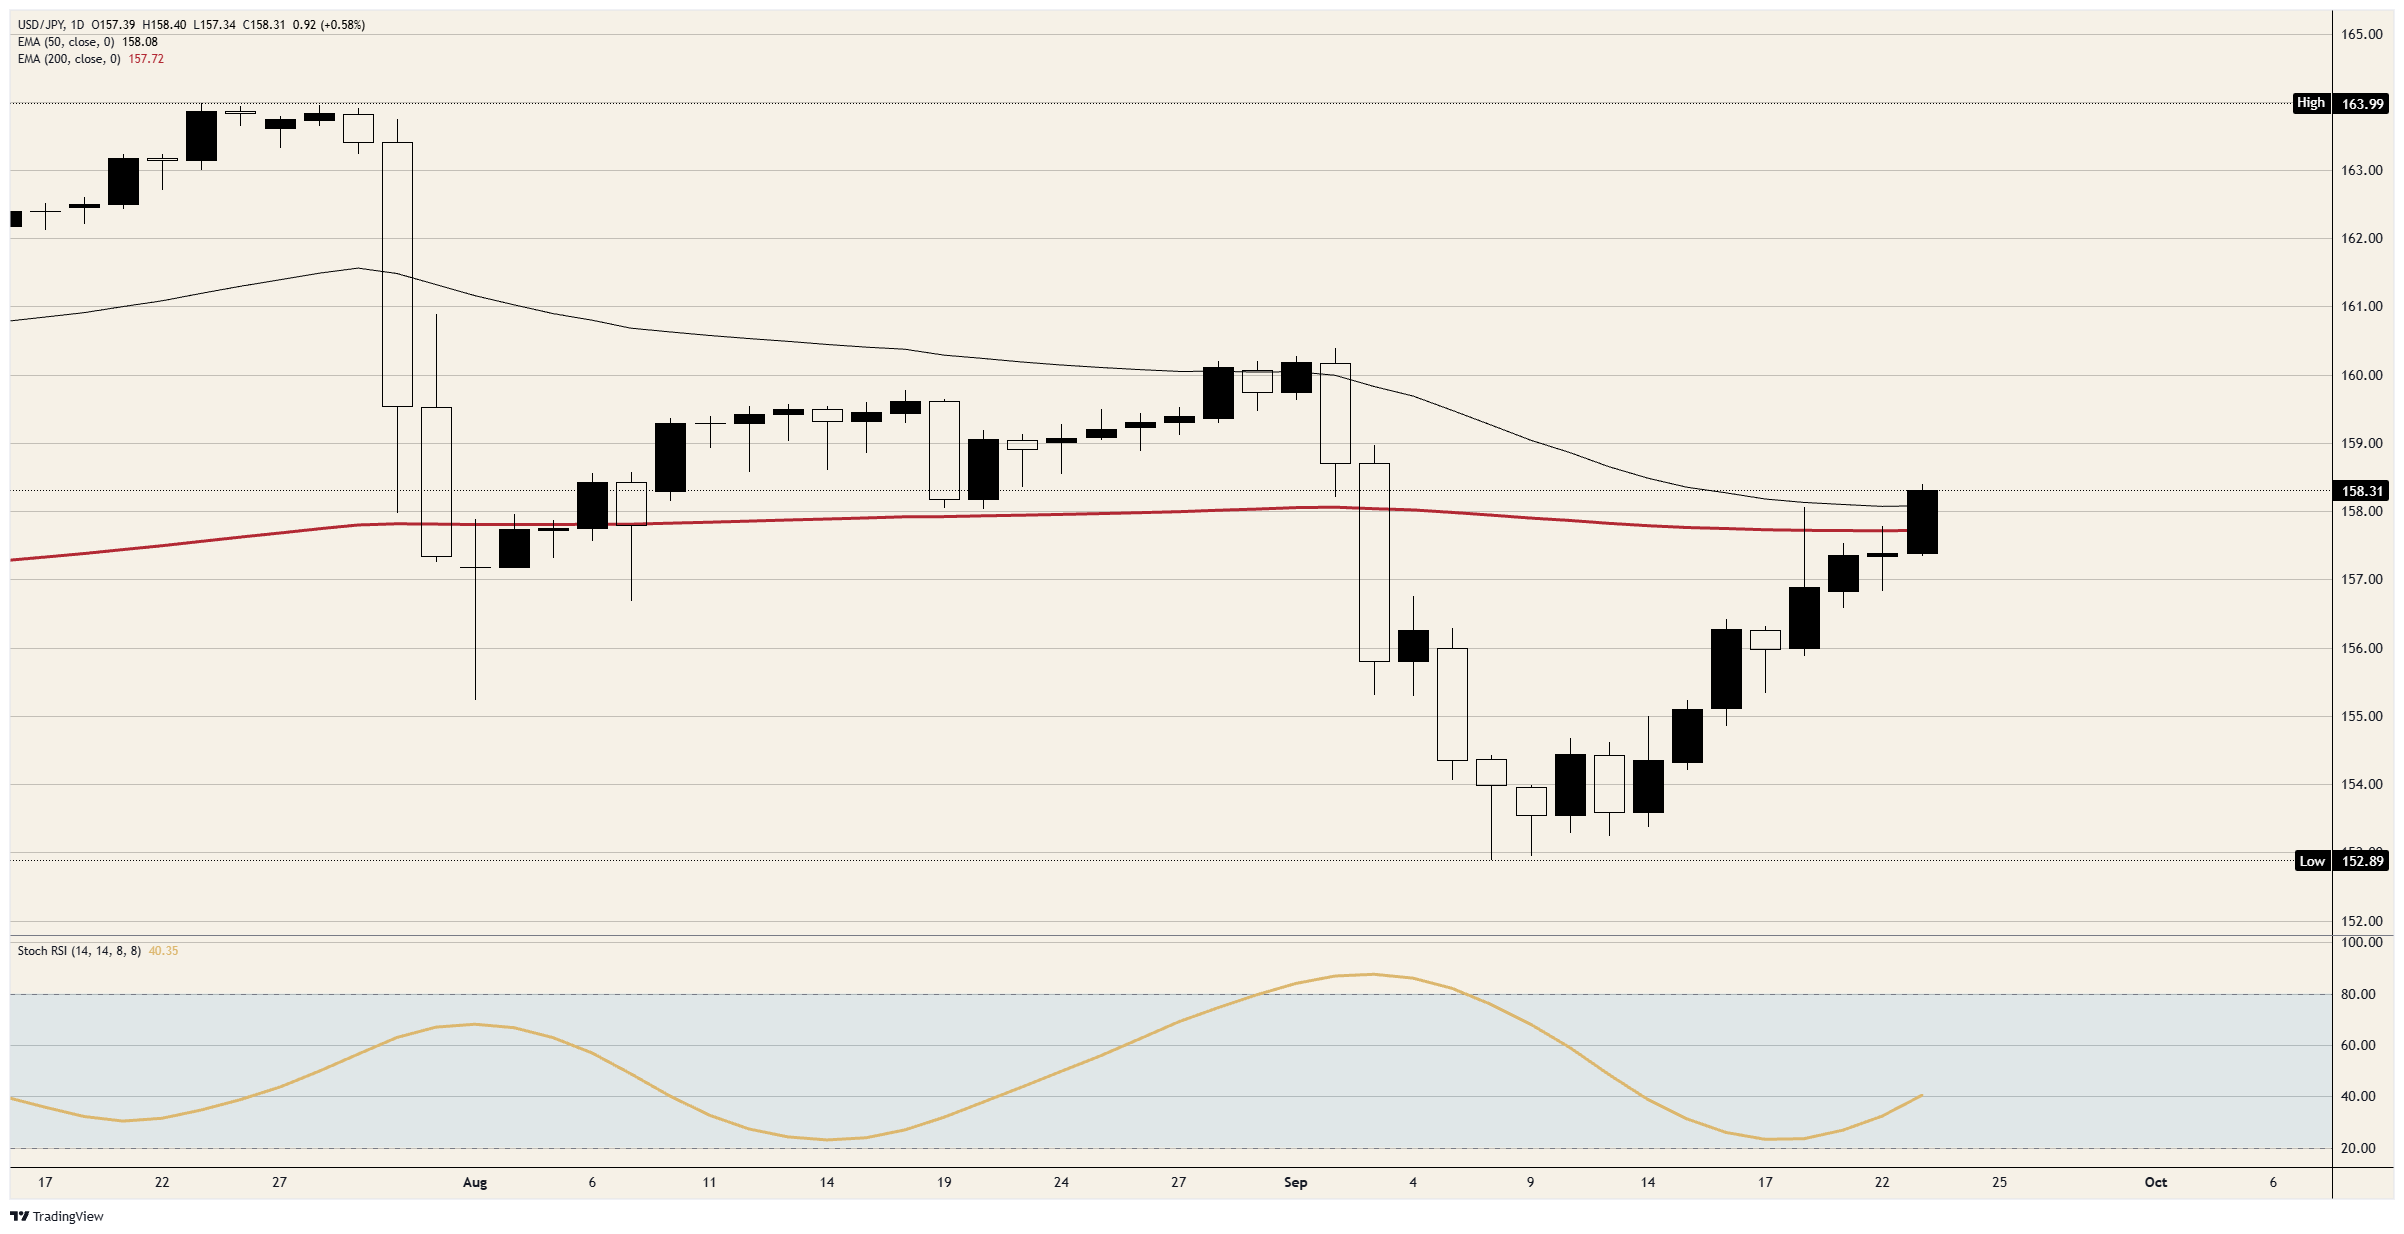
Holding up the Yen is costing Japan more each time and working for less time. USD/JPY is trading above 158.00, on track for its first daily close above its 200-day average since September 2.
Japan's Finance Ministry bought ¥15.4 trillion of Yen between July 30 and August 26, more than the ¥11.7 trillion it spent in April and May, and the US Treasury joined in on July 31. The most Japan has ever spent in a month on its currency kept USD/JPY under 160.00 for four weeks.
Japan's rate hike takes effect with the Yen weaker than on decision day
The Bank of Japan (BoJ) raised its rate to 1.25% on September 18 in a 7-2 vote, the highest since 1995, and the new rate applies from Thursday. The Fed is at 3.75-4.00%, and Fed Governor Barr argued for more increases on Wednesday. Borrowing Yen at 1.25% to hold Dollars earning close to 4% still pays.
US Treasury Secretary Bessent said on September 8 that he knew more about the BoJ's next move than traders did, and USD/JPY hit its September low near 153.00 that same day before recovering nearly three-quarters of the drop.
All of the Yen's losses since Friday came during a Japanese holiday
Japanese markets have been shut since Monday for national holidays and reopen on Thursday, the day the new BoJ rate starts. Japanese officials checked exchange rates with dealers on September 18, the step that usually comes before Japan buys Yen, and the July buying began with USD/JPY near 164.00. Tokyo's dealers return on Thursday to a USD/JPY above anything it traded on the day of that check.
Levels and bias
Resistance: Wednesday's high short of 158.50 is the first cap. Above that, 159.00 is where USD/JPY traded for most of late August, and 160.00 is where the early-September drop started.
Support: 158.00 turned from cap to floor on Wednesday. Below it, the 200-day Exponential Moving Average (EMA) just above 157.50 had capped every daily close since September 2, and 157.00 is the next level down.
Bias: Long above 157.50, aiming at 159.00 and then 160.00. The daily Stochastic Relative Strength Index (Stoch RSI) climbed to near 40 and is still rising, well short of overbought. A daily close back under 157.00 ends the long.
USD/JPY daily chart
Japanese Yen FAQs
The Japanese Yen (JPY) is one of the world’s most traded currencies. Its value is broadly determined by the performance of the Japanese economy, but more specifically by the Bank of Japan’s policy, the differential between Japanese and US bond yields, or risk sentiment among traders, among other factors.
One of the Bank of Japan’s mandates is currency control, so its moves are key for the Yen. The BoJ has directly intervened in currency markets sometimes, generally to lower the value of the Yen, although it refrains from doing it often due to political concerns of its main trading partners. The BoJ ultra-loose monetary policy between 2013 and 2024 caused the Yen to depreciate against its main currency peers due to an increasing policy divergence between the Bank of Japan and other main central banks. More recently, the gradually unwinding of this ultra-loose policy has given some support to the Yen.
Over the last decade, the BoJ’s stance of sticking to ultra-loose monetary policy has led to a widening policy divergence with other central banks, particularly with the US Federal Reserve. This supported a widening of the differential between the 10-year US and Japanese bonds, which favored the US Dollar against the Japanese Yen. The BoJ decision in 2024 to gradually abandon the ultra-loose policy, coupled with interest-rate cuts in other major central banks, is narrowing this differential.
The Japanese Yen is often seen as a safe-haven investment. This means that in times of market stress, investors are more likely to put their money in the Japanese currency due to its supposed reliability and stability. Turbulent times are likely to strengthen the Yen’s value against other currencies seen as more risky to invest in.
Top Articles
1Iran President sends defiant message to US over potential talks2Australian Dollar cools off against the New Zealand Dollar before jobs data3Gold falls below $4,300 on Fed hawkish signals4Australian Dollar tumbles amid soaring US yields, ahead of jobs data5New Zealand Dollar slides toward its range floor as US yields climb6Japanese Yen gives back most of its rally as Fed hike talk grows7Euro extends its slide as US surveys top Europe's strong reading8British Pound sells off hard as US surveys outpace the UK's9Ethereum Price Forecast: ETH takes a breather at $2,700 as activity, leverage stays calm
KUOTASI LANGSUNG


SEMUA TENTANG FOREX
Mulai Sekarang!
Daftar dan akses Pasar Global dalam waktu kurang dari 3 menit

Terhubung dengan Kami












Informasi yang disediakan di situs web ini hanya bersifat umum dan bukan merupakan nasihat keuangan pribadi. Sebelum bertindak berdasarkan informasi apa pun di situs web ini, Anda harus mempertimbangkan kesesuaian informasi tersebut dengan tujuan, situasi keuangan, dan kebutuhan Anda. Berinvestasi dalam CFD dan Kontrak Margin FX mengandung risiko yang signifikan dan tidak cocok untuk semua investor. Anda dapat kehilangan lebih dari setoran awal Anda. Anda tidak memiliki, atau mempunyai, kepentingan apa pun atas aset acuan. Kami menyarankan agar Anda mencari nasihat independen dan memastikan bahwa Anda sepenuhnya memahami risiko yang terlibat sebelum melakukan trading. Penting bagi Anda untuk membaca dan mempertimbangkan dokumen pengungkapan sebelum Anda memperoleh produk apa pun yang tercantum di situs web ini. Informasi dan iklan yang ditawarkan di situs web ini tidak ditujukan untuk digunakan oleh siapa pun di negara atau yurisdiksi mana pun jika penggunaan tersebut bertentangan dengan hukum dan peraturan setempat. Produk dan Layanan yang ditawarkan di situs web ini tidak ditujukan bagi penduduk Amerika Serikat, Malaysia, dan Thailand.
TMGM diotorisasi dan diatur di berbagai yurisdiksi.
Trademax Australia Limited, yang beroperasi sebagai TMGM, diatur oleh Australian Securities and Investments Commission (ASIC), AFSL no. 436416 dan berlokasi di Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: [email protected]
Trademax Global Limited, yang beroperasi sebagai TMGM, diotorisasi dan diatur oleh Vanuatu Financial Services Commission (VFSC), nomor registrasi 40356 dan terdaftar di 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: [email protected]
Trademax Global Markets (SE) Limited, berdagang sebagai TMGM, diberi wewenang dan diatur oleh Financial Services Authority (FSA) Seychelles dengan nomor lisensi SD224. Perusahaan terdaftar di Kantor No. 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: [email protected]
Trademax Global Markets (International) Pty Ltd, yang beroperasi sebagai TMGM, diotorisasi dan diatur oleh Financial Services Commission, Mauritius (FSC) dengan lisensi no. GB22201012, dan terdaftar di 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: [email protected]
Hak Cipta © TMGM. Semua hak dilindungi